
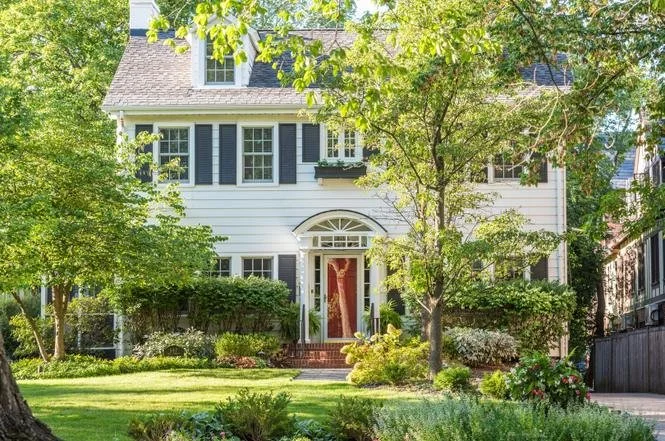
Selling a Longtime Family Home on the North Shore: A Practical Guide to Downsizing
You raised your family in this house. The height marks are still penciled inside a closet door, the dining room table has hosted thirty Thanksgivings, and somewhere in the basement there is a box labeled "misc" that nobody has opened since the first Bush administration. Now you are wondering whether it is time to sell. The good news is that the North Shore market is on your side. The harder news is that deciding when, what it will cost you in taxes, and where you will go next takes real thought.
We walk homeowners through this exact decision in New Trier Township all the time. Here is the practical version, in the order most families need it.
Why the Timing Is Better Than Most Sellers Expect
The New Trier Township market is moving fast right now. Well-located homes in Winnetka, Wilmette, Kenilworth, Glencoe, and Northfield are drawing serious buyer attention quickly, and that changes how much work a longtime owner needs to do before listing.
Here is what that means in plain terms: you probably do not need to renovate. You do not need a new kitchen or a full repaint of every room. Buyers in this market understand that a home with decades of life in it needs updating, and many of them are looking for exactly that. What you do need is a house that is clean, clear, and easy to walk through.
Cleaning Out Decades of Stuff
This is the part families put off the longest, and it is the part that matters most. Thirty or forty years in one house means thirty or forty years of accumulation: the attic, the garage, the crawl space, the closet no one opens. It feels overwhelming, but it is very doable when you break it into stages.
- Start with what you have not seen in years. If you could not say what is inside a box without opening it, you are unlikely to miss it. This is the time to let it go.
- Give things away while they are still useful. Furniture, kitchenware, books, and tools can go to charity, to neighbors, or to your children and grandchildren, who may want more of it than you think.
- Sort family keepsakes together. Photos, letters, and heirlooms deserve a slow afternoon with your family, not a rushed weekend.
- Use a storage unit as a bridge, not a destination. If you are not ready to decide on everything, a temporary unit gets the house cleared and showing well. Just set a date to go through what is in it.
You do not have to do this alone. We work with trusted partners who help families sort, clear out, and move through their belongings, along with reliable handymen for the small fixes that make a house show well. One call, and we can connect you.
Photograph the House While It Looks Its Best
Here is something many homeowners do not realize: you do not have to be sure you are moving to benefit from this. We photograph clients' homes while they look their best, such as in the fall, even when they are not certain they will sell next year. If the house is beautiful right now, we capture it. Then you have the option to use it when you are ready.
Capital Gains When You Sell a Home You Have Owned for Decades
This is the question we hear most from longtime owners: "How much of my profit will I lose to taxes?" For many families, the answer is less than they fear, and sometimes nothing at all. But if you bought your home a long time ago, it is worth understanding how the rules work.
The IRS Home Sale Exclusion
Under federal law, you can generally exclude up to $250,000 of gain from the sale of your main home, or up to $500,000 if you are married and file a joint return. To qualify, you must have owned the home and lived in it as your main residence for at least two of the five years before the sale. Those two years do not have to be consecutive. You also generally cannot have used this exclusion on another home sale in the prior two years.
Single Filer
Married Filing Jointly
Lived In
How Your Gain Is Actually Calculated
Your gain is not simply the sale price minus what you paid. It is the sale price, less your selling costs, minus your basis. Your basis starts with your purchase price and certain closing costs, and it increases with the cost of capital improvements: a new roof, an addition, a renovated kitchen or bath, new windows. Routine repairs and maintenance, like painting or fixing a leak, do not count.
This is why keeping records matters. If you have receipts, contractor invoices, or permits for major work over the years, find them now. Every documented improvement can reduce your taxable gain.
When Your Gain Is Larger Than the Exclusion
North Shore homes that were purchased decades ago can carry gains well above $500,000. When that happens, the amount over your exclusion is taxed as a long-term capital gain at the federal level. Depending on your income, that rate is 0%, 15%, or 20%. Higher-income sellers may also owe the 3.8% net investment income tax on the taxable portion of the gain if their modified adjusted gross income is above $250,000 for joint filers or $200,000 for single filers.
Illinois does not have a separate capital gains tax, but it does tax gains as ordinary income at a flat 4.95%. The good news is that gain you exclude federally generally does not show up in your Illinois income either.
If your home was inherited, or if a spouse has passed away, the picture can change in your favor. An inherited home generally receives a "stepped-up" basis equal to its value on the date of death, which can shrink the taxable gain considerably. And a surviving spouse who has not remarried can still claim the full $500,000 exclusion if the home is sold within two years of the spouse's death, as long as other requirements are met.
How Selling Affects You If You Are 65 or Older
Here is the part that surprises people: the exclusion does not change with age. The same $250,000 or $500,000 applies whether you are 45 or 85. There is no extra age-based break on the federal rules for the home sale itself. The ownership and residence tests are what count.
Where age does come into play is Medicare. Your Medicare Part B and Part D premiums can rise when your income is higher, and a large taxable gain on a home sale can raise your income for that year. Medicare premiums are generally based on your tax return from two years earlier, so a sale this year could affect your premiums down the road. For 2026 premiums, the surcharges begin when modified adjusted gross income exceeds $218,000 for joint filers and $109,000 for others. These thresholds change yearly. If your gain falls entirely within the exclusion, this usually does not come up, but if you expect a taxable gain, it is worth planning for it.
Every situation is different, so please talk with your CPA or tax advisor before you list. We are happy to work alongside them. The earlier they are involved, the more options you have.
The Biggest Question: Where Do You Go?
Ask any longtime homeowner what is holding them back from selling, and it is rarely the house or the taxes. It is this: "But where would we go?"
That is a fair question, and it deserves a real conversation, not a one-size-fits-all answer. The right move depends on how you want to live, how close you want to be to family and friends, and what you want your days to look like. There are more good options than most people realize, and we are glad to walk through every one of them with you. The best next step is to talk.
Thinking About Your Next Chapter?
Whether you plan to sell this spring or just want to know your options, we can talk through the market, the numbers, and the timing, with no pressure. And if you want, we will come photograph your home while it looks its best.
Start the ConversationSources
- IRS Topic No. 701, Sale of Your Home
- IRS Publication 523, Selling Your Home
- IRS Topic No. 409, Capital Gains and Losses
- IRS, Net Investment Income Tax
- Social Security Administration, Medicare Premiums: Rules for Higher-Income Beneficiaries
- Reed & Co., Illinois Capital Gains Tax Guide (confirm the current rate with the Illinois Department of Revenue)